Furniture Payment Strategy Calculator
Enter your furniture price and current financial situation to see which payment method saves you the most money.
Your Situation
Cost Breakdown
| Method | Total Cost | Notes |
|---|
Why this choice?
Enter details and click Calculate to see your options.
You just found the perfect sofa. It’s exactly what your living room needs, but the price tag makes you hesitate. Should you swipe your credit card? Take out a loan? Or wait until you’ve saved enough cash? The way you pay can change how much that couch actually costs you, and it affects your financial health long after delivery day.
Most people don’t think about payment methods when they’re excited about new decor. But choosing between furniture finance, credit cards, and cash isn’t just about convenience-it’s about strategy. Some options save you money through rewards; others cost you hundreds in interest. Let’s break down exactly how to choose the right method for your situation, without falling into common debt traps.
The Cash Approach: When It Makes Sense
Paying with cash is the simplest option. No interest, no fees, no future payments haunting you. If you have the funds sitting in a savings account earning less than 4% interest, and the furniture store offers a discount for upfront payment (which happens more often than you’d think), paying cash can be a smart move.
But here’s the catch: draining your emergency fund for a dining table leaves you vulnerable. If your car breaks down next month, you might end up using a high-interest credit card anyway. A good rule of thumb? Only pay cash if the purchase doesn’t drop your liquid savings below three months’ worth of expenses. In Birmingham, where rent prices are climbing, keeping a buffer is crucial.
Cash also gives you negotiating power. Salespeople often have quotas to meet at the end of the month. Walking in with cash-or a debit card ready to go-can sometimes shave 5-10% off the sticker price on clearance items. Always ask: "Is there a better deal if I pay today?"
Credit Cards: Rewards vs. Interest Rates
Credit cards are popular for furniture purchases because they offer protection and perks. Many major retailers like DFS or IKEA accept Visa and Mastercard. If you pay your balance in full within the grace period (usually 30-55 days), you effectively borrow money for free.
The real value lies in rewards. If you have a card offering 2% cash back, a £1,000 wardrobe gets you £20 back. That’s free money. Plus, many premium travel cards offer extended warranties on electronics and furniture, which standard manufacturer warranties don’t cover. For example, some American Express cards add an extra year to the warranty on items over £100.
| Scenario | Cost Impact | Best For |
|---|---|---|
| Paid in Full Next Month | £0 interest + rewards | Saving discipline, small purchases |
| Carried Balance (18% APR) | High interest costs | Emergency only |
| New Card Promo (0% for 12m) | £0 interest if paid by deadline | Large one-off purchases |
However, carrying a balance is dangerous. Average UK credit card interest rates hover around 18-20%. On a £2,000 order, that’s roughly £30-£40 in interest per month if you don’t pay it down quickly. Unless you have a specific 0% introductory offer, paying off a large furniture bill slowly on a standard card usually wipes out any reward gains.
Furniture Store Financing: The "Interest-Free" Trap
Stores love pushing their own financing plans. You’ll see signs saying "0% Interest for 24 Months." Sounds great, right? It can be, but read the fine print. These deals often come with strict conditions.
First, check for setup fees. Some retailers charge £99 or more just to open the account. Second, understand the "deferred interest" clause. This means if you miss one payment or fail to pay off the full balance by the end of the promotional period, you get hit with all the interest accrued from day one. Not just the remaining balance-the whole thing. One missed payment could cost you hundreds.
Also, consider your credit score impact. Opening a new store credit line can temporarily lower your score due to hard inquiries. If you’re planning to apply for a mortgage soon, avoid opening new lines of credit right before applying.
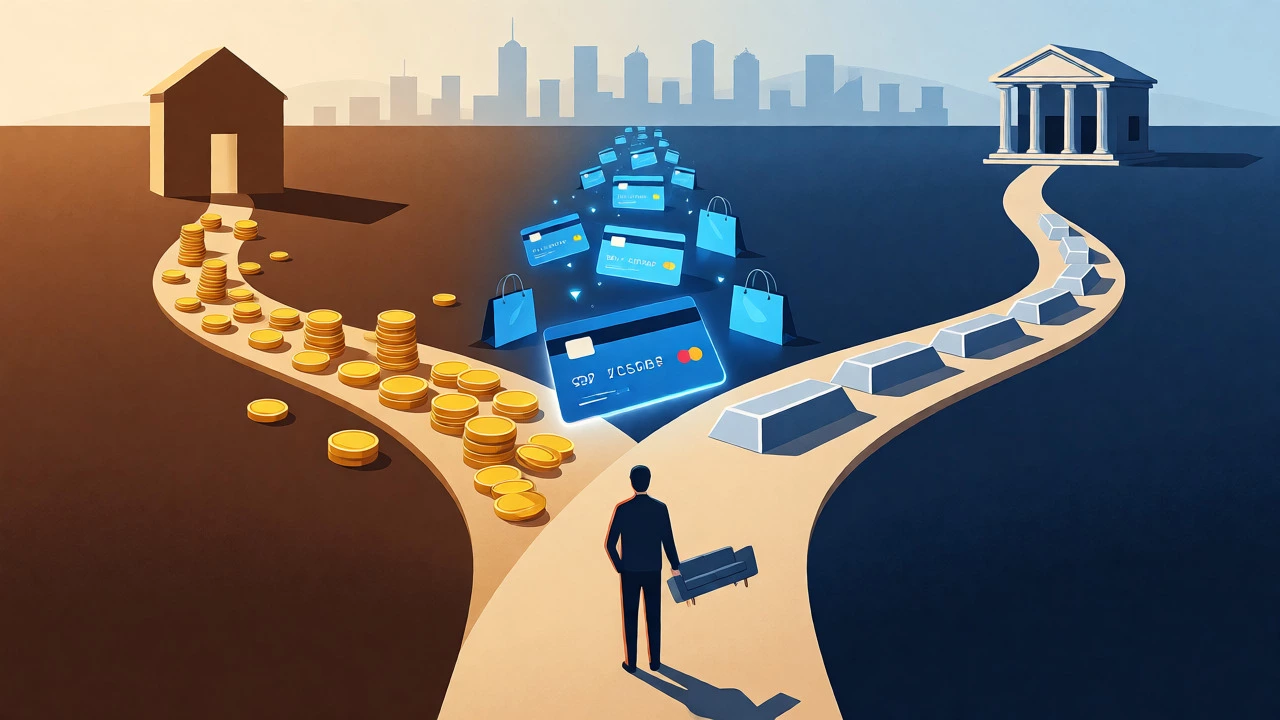
Buy Now, Pay Later (BNPL): Convenience or Debt Spiral?
Services like Klarna, Clearpay, and PayPal Pay in 3 have exploded in popularity. They split the cost into four interest-free installments every two weeks. For smaller items-like a £300 coffee table-this works well. It’s easy to manage, and as long as you automate the payments, you won’t miss a beat.
But BNPL becomes risky when used for big-ticket items. Splitting a £1,500 sofa into four payments of £375 feels manageable. But if you stack multiple BNPL loans across different stores, you might lose track of total monthly obligations. Unlike credit cards, BNPL services don’t always report to credit bureaus positively unless you’re late. So you get no credit-building benefit, but you still risk damage if you default.
Use BNPL for items under £500 where you know you can clear the balance within two months. Avoid it for multi-thousand-pound orders unless you have a clear payoff plan.
Personal Loans: The Middle Ground
If you need to spread the cost over 12-36 months and want predictable payments, a personal loan from your bank might be better than store financing. Current fixed-rate personal loans in the UK range from 3% to 8% depending on creditworthiness. Compare this to the hidden risks of deferred interest store plans.
A key advantage: you own the asset outright immediately. With some store financing schemes, the retailer retains a lien on the goods until fully paid. If you move house or sell the item early, dealing with that paperwork can be annoying. Personal loans give you clean title ownership from day one.
Decision Checklist: Which Method Fits You?
Still unsure? Run through this quick decision tree:
- Do you have the cash? Yes → Negotiate a discount and pay cash/debit. No → Continue.
- Can you pay off the full amount within 30 days? Yes → Use a rewards credit card. No → Continue.
- Is there a genuine 0% APR offer (not deferred interest)? Yes → Check fees and repayment schedule. No → Continue.
- Is the item under £500? Yes → Consider BNPL. No → Consider a personal loan.
Remember, the cheapest way to pay isn’t always the most convenient. Sometimes waiting six weeks to save the cash saves you £150 in interest and fees. Other times, leveraging a 0% promo lets you keep your cash invested elsewhere while spreading the cost.
Common Pitfalls to Avoid
Don’t let sales pressure rush you. "This offer expires today!" is a classic tactic. If the terms aren’t clear, walk away. You can almost always find similar furniture elsewhere.
Also, beware of insurance add-ons. Stores often push "protection plans" costing 10-15% of the item price. Read your home insurance policy first-you might already be covered for accidental damage. Don’t double-pay.
Finally, never co-sign a furniture loan with someone else unless you’re prepared to pay it yourself. If their finances slip, yours take the hit.
Is it better to pay for furniture with cash or credit?
It depends on your ability to repay. If you can pay the credit card balance in full within the grace period, credit is better due to rewards and buyer protection. If you carry a balance, cash is cheaper because you avoid high interest rates (often 18%+).
What is deferred interest in furniture financing?
Deferred interest means no interest is charged during the promotional period (e.g., 12 months). However, if you do not pay off the entire balance by the end of that period, you are charged interest retroactively from the date of purchase, not just on the remaining balance.
Does buying furniture on finance affect my credit score?
Yes. Applying for finance triggers a hard inquiry, which can slightly lower your score. Responsible management (on-time payments) helps build credit over time. Missed payments can significantly damage your score.
Are Buy Now Pay Later services safe for furniture?
They are safe if managed carefully. BNPL services like Klarna don't charge interest if paid on time. However, they lack the robust dispute resolution processes of credit cards, making them riskier for expensive items if delivery goes wrong.
Should I take out a personal loan for furniture?
A personal loan is a good option for large purchases (£1,000+) where you need longer repayment terms than credit cards allow. Fixed rates provide predictability, and you own the goods outright immediately, unlike some store financing plans.
Write a comment